Cheapest Home Insurance in Miami, FL


Why you can trust HoneyQuote
HoneyQuote is not an insurance company. We are a licensed independent agency, and our editorial content is written and reviewed by licensed insurance professionals. It is not submitted to the carriers or partners we work with for approval, and no carrier pays for placement on this page. The rate figures here come from real quotes collected through our platform, and our data sets out how they are calculated and when they were last refreshed.

Homeowners insurance in Miami costs an average of [$X HQ DATA]/ month, more than almost anywhere else in Florida, and the reasons are specific to this city rather than the state. Miami-Dade is one of only two counties held to the High-Velocity Hurricane Zone building code, wind exposure drives the rating, and roof age decides whether many applications are accepted at all. This page covers what coverage actually costs here, which companies are writing new policies in Miami right now, and what to do if yours has been non-renewed.
HoneyQuote is a licensed independent agency comparing 20+ carriers across Florida, so you can see real Florida home insurance quotes and find the best rate, with all the coverage you need: Get a quote in under 30 seconds, submit your application in less than 5 minutes.
The cheapest home insurance in Miami averages [HQ $/yr] a year across the carriers writing here, against a Miami average of [HQ $/yr]. All figures on this page are averages for [HQ dwelling value] of dwelling coverage with a [HQ deductible] deductible, calculated from real quotes as of [HQ date]. Your own price will differ, because distance to water, roof age and flood zone. Read more on our data here.
Cheapest is not the same as best value, and in Miami the gap matters more than it does inland. A low premium on a policy with a 10% hurricane deductible can cost far more than a higher premium at 2% the first time a named storm crosses Miami-Dade. The table below shows the five cheapest carriers writing in Miami with their average annual rate, so you can see where your quote sits before you start calling.
| Insurance company | Avg. annual rate |
|---|---|
| [HQ] | $[HQ] |
| [HQ] | $[HQ] |
| [HQ] | $[HQ] |
| [HQ] | $[HQ] |
| [HQ] | $[HQ] |
Getting home insurance in Miami takes three steps and, for most homeowners, under 30 minutes.
Enter your ZIP
Get matched with real quotes from carriers writing in Miami-Dade.
Compare your options
Coverage and pricing side by side, including the hurricane deductible on each.
Approved in 24 hours
Continue online or with a licensed agent.
The best home insurance in Miami depends less on which company you pick and more on what kind of house you own. A 1970s house in Westchester, a waterfront condo in Brickell and a new build in Doral are three different underwriting problems, and the carriers that want them are not the same. Below are the four situations Miami homeowners run into most often, with what each one does to your price and who will still write it.
Best home insurance for older homes in Miami
Older homes in Miami average [HQ $/yr] a year, and [HQ #] carriers will still write them. Roof age is the single most common reason a Miami application is declined, and the line most underwriters draw is 2002, when Florida adopted the statewide building code written after Hurricane Andrew. A house built before that date is assessed differently even if the roof has since been replaced.
House insurance in Miami and homeowners insurance in Miami are the same product; the policy that covers the structure, your belongings and your liability. Property insurance is the broader term an agent will use, and for most Miami homeowners it means the same policy plus the separate flood and wind coverage that sits alongside it.
Two inspections decide most of this. A four-point inspection covers the roof, plumbing, electrical and HVAC, and in Miami the two things that most often stop an application are cast-iron plumbing and an outdated electrical panel. A wind mitigation inspection is the one worth ordering before you shop, because it can move the premium more than switching carriers does. Construction matters too: concrete block homes rate better than wood frame here, which is part of why so much of Miami is built in block.
Learn about all homeowners insurance rating factors.
| Roof age | Avg. annual premium | Still widely insurable in Miami-Dade? |
|---|---|---|
| 0 to 10 yrs | $[HQ] | Yes |
| 10 to 20 yrs | $[HQ] | Yes |
| 20+ yrs | $[HQ] | Limited, fewer carriers |
Best home insurance for flood-zone and near-coast homes in Miami
Homes near the coast or in a flood zone in Miami run [HQ $/yr] to [HQ $/yr] a year, depending on how close you are to the water.
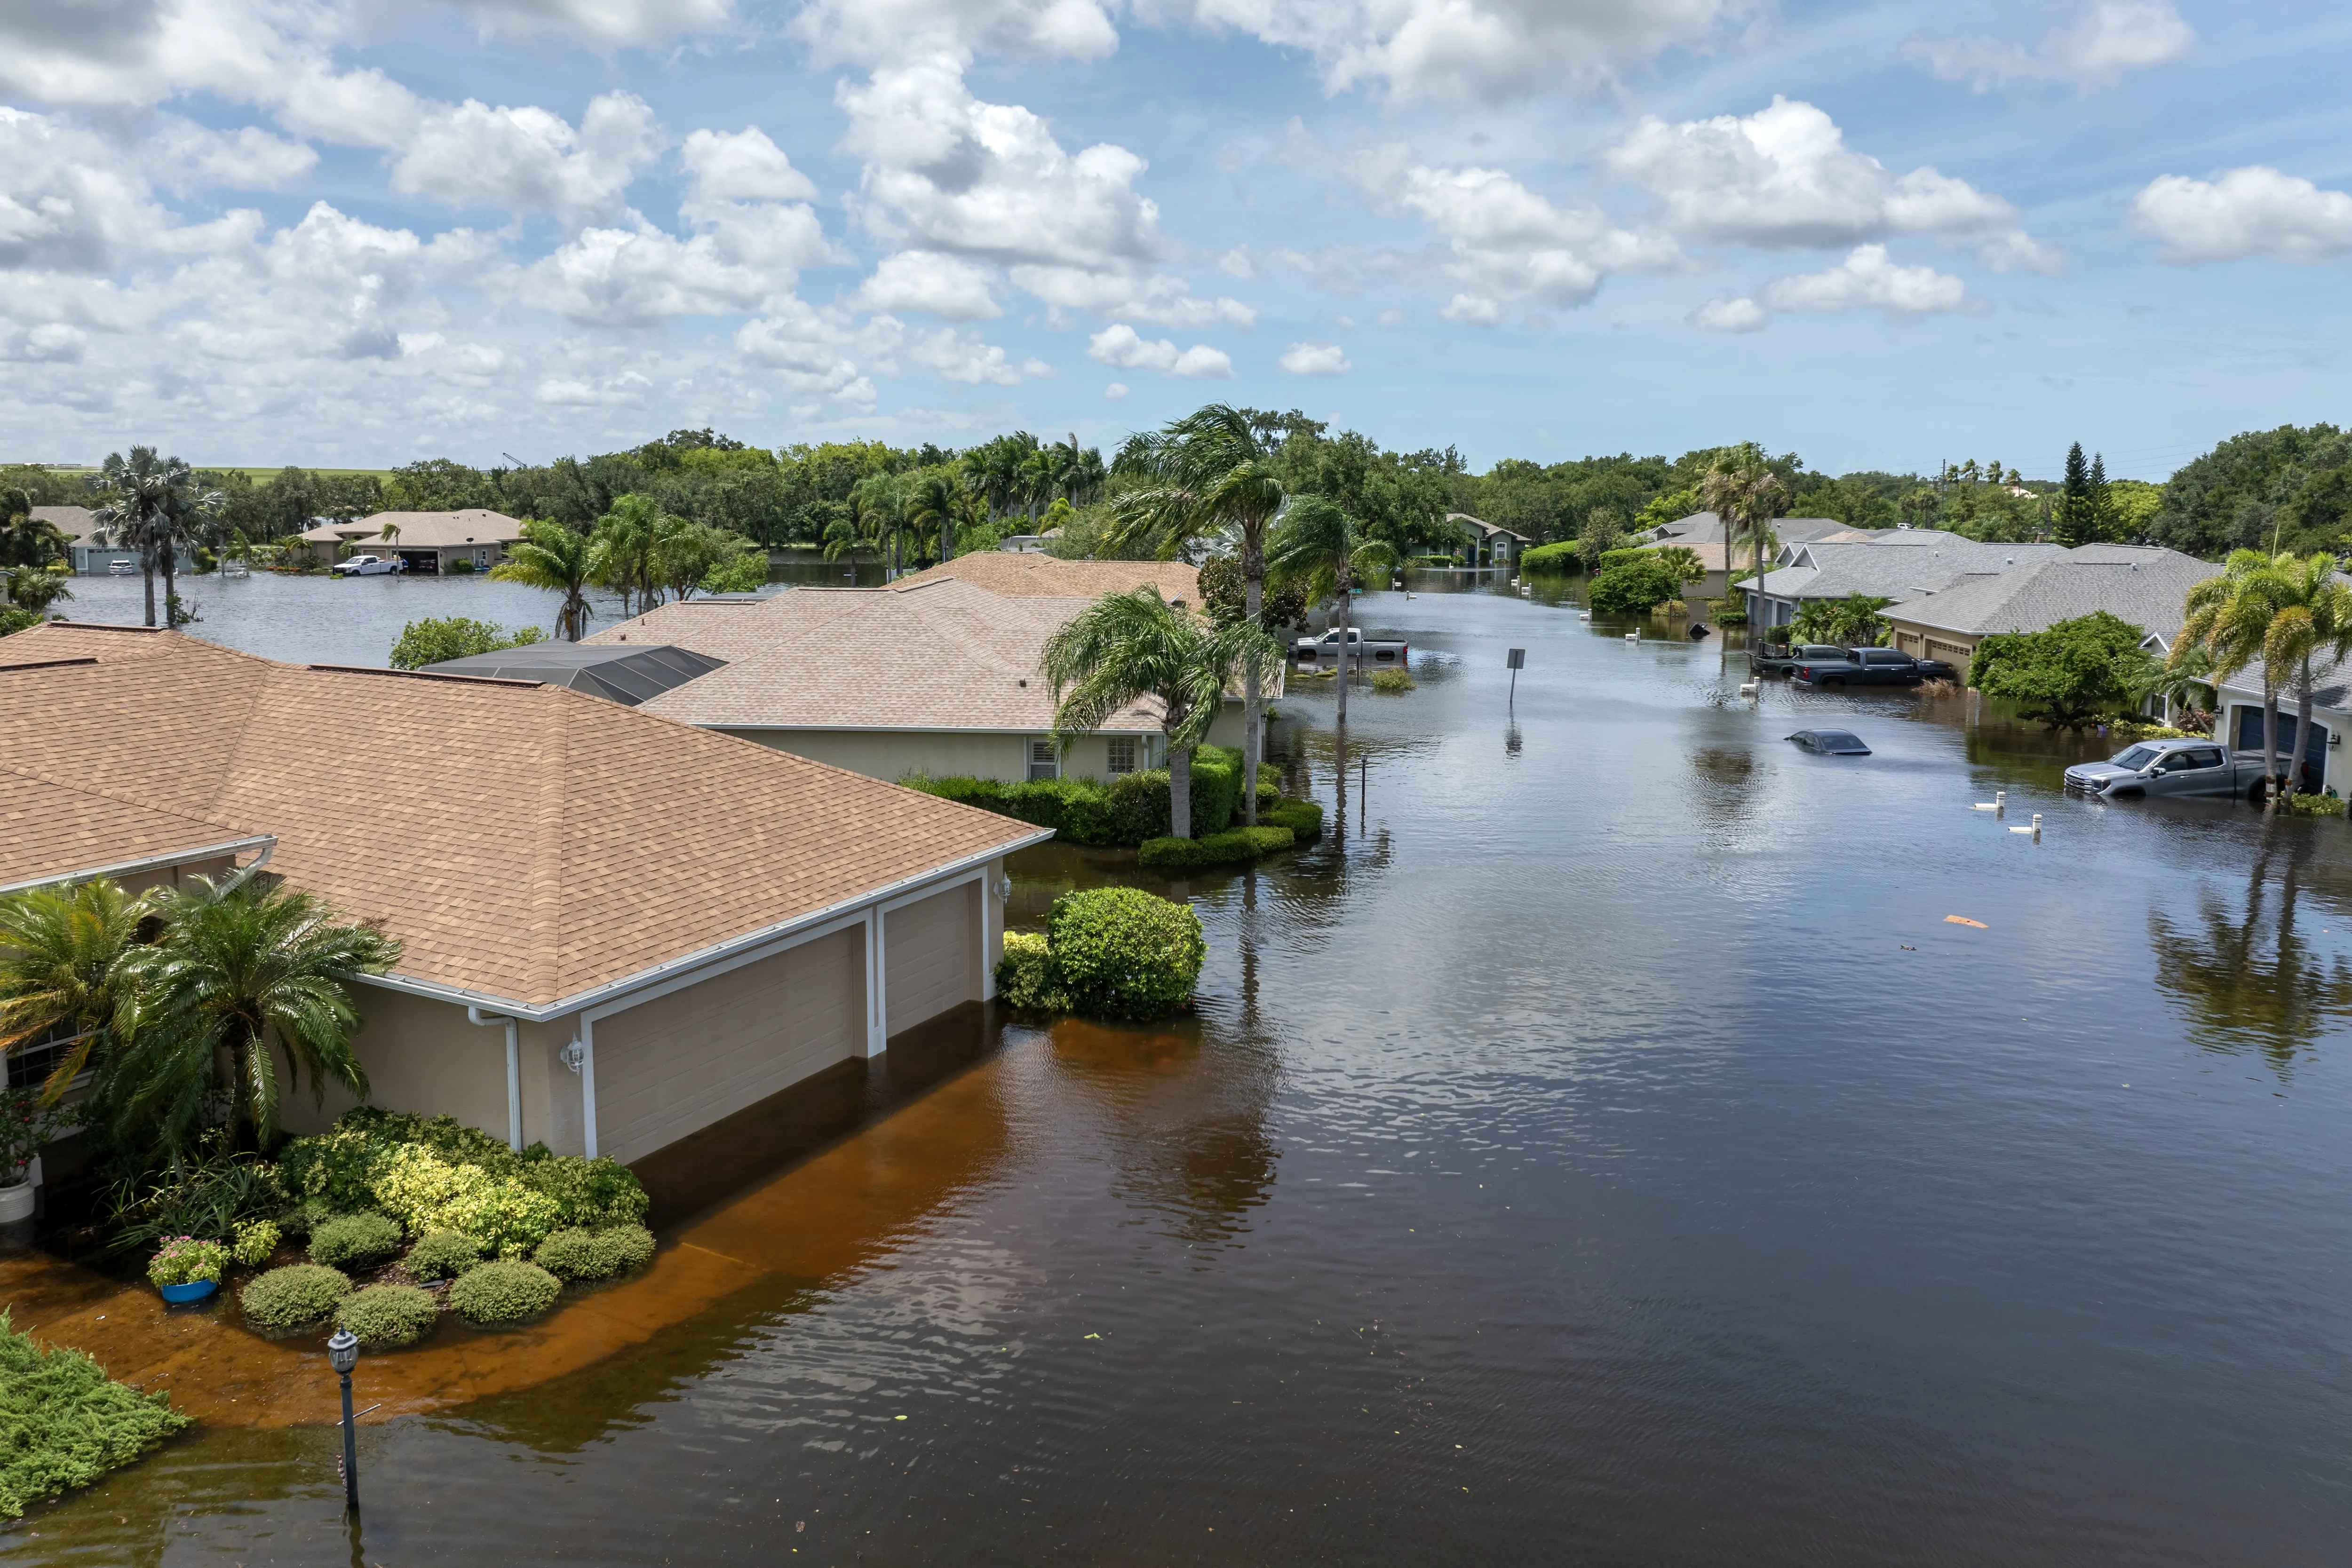
Here is the part most Miami homeowners never hear about: Home insurance does not cover flooding. Not here, not anywhere in the country. If water rises and comes into your house, your home insurance will not pay for it. Flood insurance is a separate policy you buy on top of your home insurance, and in Miami that is not a technicality, as plenty of homes that flood here are nowhere near the beach.
| Flood zone / distance to water | Avg. annual premium | NFIP or private? |
|---|---|---|
| Zone X (low risk) | $[HQ] | Flood optional |
| Zone AE | $[HQ] | NFIP or private |
| Zone VE / coastal | $[HQ] | Private often wins |
Best home insurance with hurricane coverage in Miami
A 2% hurricane deductible on a typical Miami home means about [HQ $] out of pocket before your coverage kicks in.
Wind is the main thing you are buying protection against in Miami; It is the biggest single reason your bill is what it is, and it is the part of the policy most likely to be tested. Miami-Dade and Broward are the only two counties in Florida held to the strictest hurricane building rules in the state. Homes here are built to stand up to 175 mph winds, and windows, doors and roofing have to be approved by the county before anyone can fit them. Those rules are why Miami homes come through storms that flatten houses elsewhere, and they are also why materials, labour and insurance all cost more here.
Your hurricane deductible is not a flat dollar amount like a normal one. Rather, it is a percentage of what your home is insured for. A normal deductible might be $2,500 no matter what happens. A hurricane deductible of 2% on a home insured for $450,000 is $9,000. It also resets for each named storm, and it sits separately from the regular deductible you pay for everything else.
So what do the options actually mean for you? On that same $450,000 home, 2% is $9,000 out of pocket, 5% is $22,500 and 10% is $45,000, every time a named storm damages your house. A higher percentage lowers your bill every year and raises what you pay in the one year it matters. The right choice comes down to a single question: how much cash could you actually get your hands on in the week after a hurricane? That is a different question from which policy is cheapest and will help you decide what the best home insurance looks like for you.
| Hurricane deductible | Out of pocket on a $450,000 Miami home | Premium impact |
|---|---|---|
| 2% | $9,000 | [HQ] |
| 5% | $22,500 | [HQ] |
| 10% | $45,000 | [HQ] |
Best home insurance after being dropped or non-renewed in Miami
Non-renewed in Miami? [HQ N] companies are still writing new policies here, averaging [HQ $/yr] a year.
Non-renewals are common along the coast at the moment, and Miami sees more of them than most places. Insurance companies limit how many homes they will cover in any one county, so that a single hurricane cannot wipe them out. When a company decides it holds too much of Miami-Dade, it stops renewing policies there. It usually picks by ZIP code, roof age or claims history rather than by customer.
So being dropped is not a verdict on your house. It almost never means your home cannot be insured. It means that one company is pulling back from your area, and a different company with room on its books may want exactly the home yours is. People who have been non-renewed often end up paying less than they expected once they shop properly, because they were on an old policy that had not been re-priced in years.
You have three routes. The first is a regional Florida company: these are the smaller insurers that write most of the coastal business now, and they are often the best fit for a Miami home even if you have never heard of them. The second is Citizens, the state-run insurer that exists for when nothing else is available. It is a safety net, not a destination, and companies have been steadily taking policies back off it since 2024. The third is fixing what triggered the non-renewal, usually the roof, and re-shopping from a stronger position.
Whichever route you take, start before your policy actually ends. Even a short gap makes the next policy harder to get and more expensive, and it breaks the terms of your mortgage. Book a wind mitigation inspection and a four-point inspection first, because both open up companies that would otherwise say no. If you are close to the lapse date, tell the agent, because some companies can move faster than others.
A company can have thousands of reviews and still handle claims badly, or have fewer reviews and a loyal base that stays with it. This table ranks the insurers serving Miami by how positively customers rate them, and by what those customers consistently praise: claims handling, responsiveness and fair payouts.
| # | Carrier | Avg. rating | Reviews | Years in business | Writing in Miami? |
|---|---|---|---|---|---|
| 1 | [HQ] | [HQ] | [HQ] | [HQ] | [HQ] |
| 2 | [HQ] | [HQ] | [HQ] | [HQ] | [HQ] |
| 3 | [HQ] | [HQ] | [HQ] | [HQ] | [HQ] |
| 4 | [HQ] | [HQ] | [HQ] | [HQ] | [HQ] |
| 5 | [HQ] | [HQ] | [HQ] | [HQ] | [HQ] |
Carriers serving Miami ranked by positive-sentiment score, with average rating and the volume of positive reviews behind it. Pulled from third-party review sources and sentiment analysis, refreshed periodically.
The average cost of home insurance in Miami is [HQ $/yr] a year, or [HQ $/mo] a month, for a [HQ dwelling value] home with a [HQ deductible] deductible, based on our data as of [HQ date].
How much is home insurance in Miami depends on three things more than any other: how close you are to open water, how old your roof is, and which flood zone your address falls in. That is why two houses of the same size in the same city can be thousands of dollars apart.
The table below breaks the average down by neighbourhood, so you can see roughly where your address lands before you request a quote.
| Neighbourhood (ZIP) | Avg. annual rate | Vs. Miami average |
|---|---|---|
| Brickell ([ZIP]) | $[HQ] | [HQ] |
| Coral Gables ([ZIP]) | $[HQ] | [HQ] |
| Coconut Grove ([ZIP]) | $[HQ] | [HQ] |
| Little Havana ([ZIP]) | $[HQ] | [HQ] |
| Kendall ([ZIP]) | $[HQ] | [HQ] |
| Doral ([ZIP]) | $[HQ] | [HQ] |
| Westchester ([ZIP]) | $[HQ] | [HQ] |
What a wind mitigation inspection is worth in Miami
A wind mitigation inspection is the cheapest way to lower a Miami premium, and most homeowners either have never had one or had one so long ago the credits have lapsed. An inspector fills in a standard state form, OIR-B1-1802, recording how the roof is attached, what is under the covering, the shape of the roof, and whether the openings are protected. Each of those earns a credit, and because Miami-Dade is in the High-Velocity Hurricane Zone the credits here are larger than anywhere else in Florida.
The table below shows what each feature is worth on a typical Miami policy, so you can see whether the inspection pays for itself before you book one. It usually does.
| Wind mitigation feature | What it is | Typical credit on a Miami policy |
|---|---|---|
| Roof covering | Whether the roof meets the current Florida Building Code | [HQ] |
| Roof deck attachment | How the decking is fastened to the trusses | [HQ] |
| Roof to wall connection | Clips, single wraps or double wraps | [HQ] |
| Roof geometry | Hip roofs outperform gable roofs in high wind | [HQ] |
| Secondary water resistance | A sealed layer under the covering | [HQ] |
| Opening protection | Impact glass or approved shutters on every opening | [HQ] |
Home insurance in Miami-Dade came down in 2026 for the first time in years. Citizens cut rates by an average of 14.0% across about 42,000 Miami-Dade homes [HQ to verify] in January, the second biggest drop of any county in Florida and well ahead of the 8.7% statewide average.
The reason is a change in the law rather than a change in the weather. Florida closed two loopholes that had made insurance lawsuits unusually expensive here, and companies started writing in Florida again. More companies competing for Miami business means the quote you were given two years ago is probably not the best one available now, and it is worth shopping again even if nothing about your house has changed.
Sources: Florida Governor's office, 12 January 2026 · Citizens Property Insurance
| Year | Avg. Miami rate | Year on year change | What drove it |
|---|---|---|---|
| 2023 | $[HQ] | - | [HQ] |
| 2024 | $[HQ] | [HQ]% | [HQ] |
| 2025 | $[HQ] | [HQ]% | [HQ] |
| 2026 | $[HQ] | [HQ]% | [HQ] |
A short intro answering "are home insurance rates going up in Florida" — a high-volume, anxiety-driven query.
Compare home insurance quotes in Miami
Competitive prices on the coverage you need.
Sources
HoneyQuote's rate figures come from our own quote data: real premiums from real coastal homes. We publish how we collect and calculate our data so you can check our work. Where we cite market-wide trends, we use primary government and industry sources rather than other insurance sites.
- HoneyQuote Research: read more about insurance through studies and data.
- HoneyQuote Methodology: how we collect quote data, what's included, and what we exclude.
About HoneyQuote — Editorial Trust Block
A short editorial trust block communicating data credibility and editorial independence. Note: this is not in the footer nav — it sits at the very bottom of the page content, just above the sitewide footer. Suggested: “HoneyQuote is not an insurance company. We publish data-backed resources to help homeowners compare home insurance in Florida and beyond. Our content is written and reviewed by licensed insurance professionals. Our editorial content is not subject to review by carriers or partners. Rate data is based on real quotes collected through the HoneyQuote platform, updated continuously.”
Lorem Ipsum
Lorem ipsum dolor sit amet, consectetur adipiscing elit

Our team is here for you
Competitive prices on the coverage you need.
Get my Miami home insurance quote in 30 seconds.